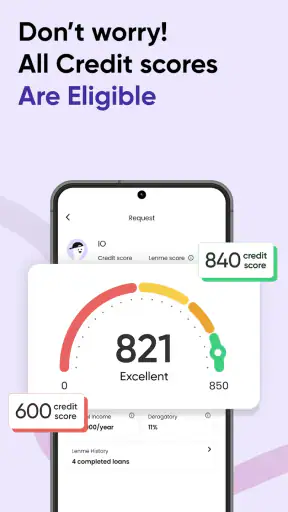
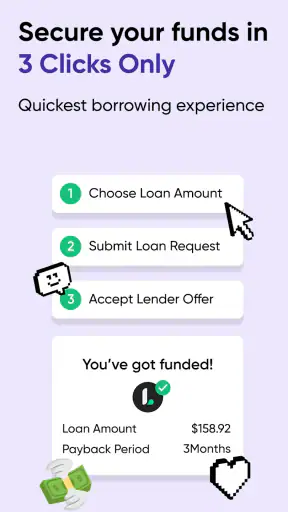
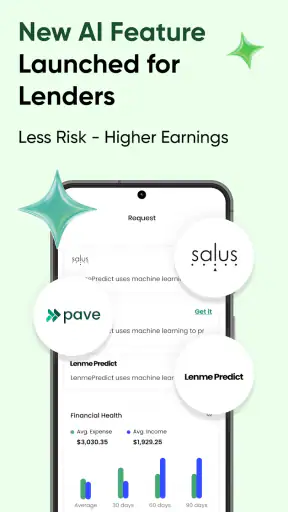
When an unexpected bill arrives, the hardest part is often not finding a financial app but deciding whether borrowing through one is genuinely useful after the immediate pressure has passed. I spent time with Lenme: Borrowing and Lending, a free finance app from Lenme: Borrow and Lend, to see whether it feels like a practical tool or simply an attractive shortcut during a stressful moment. My first impression was positive: the app is focused on connecting people with borrowing and lending opportunities rather than trying to become a complete banking replacement.
That focus gives it a clear purpose. Lenme is aimed at people looking for quick cash advances or personal loan opportunities, while also presenting possibilities for users interested in lending. It is available to an Everyone audience, runs on Android devices using version 8.0 or later, and has reached over 500 thousand installs. Those details make it approachable, but accessibility should not be confused with low financial risk. The app can make the search process feel easier; it cannot make repayment obligations disappear.
How Lenme holds up beyond the first week
The first-week appeal is convenience with an important catch
The strongest part of my first week was the straightforward reason to open the app. If I needed to explore a personal loan or cash advance, I could approach that task in one place instead of jumping between unrelated lenders, search results, and financial websites. The appeal is especially clear when time matters and I want to understand what opportunities may be available before deciding what to do next.
I also liked that the concept works in both directions. A borrower can look for funding, while someone interested in lending can investigate opportunities presented through the platform. That makes Lenme feel different from a conventional budgeting app, where the main job is tracking money already in an account. Here, the central activity is evaluating a possible financial arrangement.
The app’s AI-powered lending angle adds to that early curiosity. It suggests a more guided approach than simply browsing a long list of generic loan advertisements. In practice, though, I would treat any automated guidance as a starting point rather than a recommendation I should accept without checking. Financial decisions need context: repayment timing, total cost, consequences of missing a payment, and whether the amount actually solves the original problem.
A realistic example is a short gap between an essential expense and payday. I might use Lenme to investigate a modest borrowing option, compare the terms I am shown with my actual budget, and then decide whether the expense can wait. The useful workflow is not “open the app and borrow immediately.” It is “open the app, gather enough information to make a deliberate choice, and stop if the numbers do not fit.” That distinction is one of the most important things I took from using it.
The app has a 4.2 average from around 22 thousand ratings, which suggests that many people find the basic experience worthwhile. I can understand that reaction because the purpose is easy to grasp and the first interaction feels more focused than searching randomly across the internet. Still, a good first week does not automatically prove lasting value. A finance app earns a permanent place only when it remains useful between urgent moments.
What I would check before accepting any opportunity
Lenme should not be treated as a magic source of free money. Before accepting an offer, I would write down the amount I actually need, the date I expect to repay it, and the maximum total cost I can manage. I would also check whether the repayment schedule clashes with rent, utilities, food, or existing commitments. This simple preparation prevents the app’s convenience from encouraging a larger loan than the situation requires.
Another practical habit is to compare the opportunity with familiar alternatives. A credit union, a bank, an employer advance, or a direct conversation with a service provider may be better in a particular situation. Those options can have different eligibility rules and costs, but the key point is that Lenme is one route, not automatically the best route. I would use it as a comparison tool within a broader decision, not as my only source of financial information.
For potential lenders, the same caution applies in reverse. A lending opportunity should be judged as a financial risk, not as a way to earn easy money. I would want to understand how funds are committed, what information is available about the opportunity, and how comfortable I am with the possibility that money may not behave like cash kept in a savings account. The platform’s convenience does not remove the need for personal risk limits.
Month-to-month value depends on your financial pattern
After the initial novelty fades, Lenme becomes more useful for a specific group: people who occasionally need to investigate short-term borrowing options and want a repeatable place to begin. If that describes me, the app can become part of a monthly financial routine. I might review an upcoming expense, decide whether borrowing is necessary, and use the app only when the numbers support that decision.
That is a narrower kind of recurring value than a budgeting app provides. A budgeting tool can help me every week by showing spending patterns, planning bills, and keeping goals visible. Lenme matters more selectively. Its value appears when I need to explore a borrowing or lending opportunity, not necessarily every day. I see that as a strength if I want a specialized tool and a weakness if I expect a complete personal finance dashboard.
The app’s 4.7 thousand reviews indicate that the experience has generated substantial user feedback, but feedback volume alone does not tell me whether it will fit my financial life. The better question is whether I have a genuine recurring use case. Someone who rarely borrows and has stable savings may open Lenme once and never need it again. Someone dealing with irregular income may find it more relevant, provided they use it carefully and do not turn occasional borrowing into a routine way of covering ordinary spending.
One non-obvious benefit is that a dedicated lending app can create a pause between worry and action. Instead of accepting the first offer that appears in a search engine, I can make the borrowing decision a separate task. I can review the amount, consider alternatives, and decide whether repayment is realistic. That pause is valuable, but only if I deliberately preserve it. Fast access can just as easily shorten the time available for reflection.
The maintenance burden is low, but the financial work remains yours
From a technical point of view, Lenme is not the kind of app that demands constant content management. I would not need to maintain a complex spreadsheet inside it or build a detailed financial system before seeing value. The current version is 26.6.1, and the app is free to install, which lowers the barrier to keeping it available for occasional use. There are in-app purchases ranging from $1.99 to $399.99 per item, so I would pay attention to any purchase screen and avoid assuming that every part of the experience is cost-free.
The larger maintenance burden is behavioral. If I borrow through the app, I need my own reminder system for repayment dates, a realistic cash-flow plan, and a record of what I agreed to. I would not rely on simply remembering that a loan exists. A useful routine would be to note the obligation immediately, reserve the repayment amount when possible, and review the plan before taking on another commitment.
This is where Lenme differs from a traditional bank account. A bank app usually gives me an ongoing view of balances and transactions. Lenme is more event-driven: I open it because I am considering a lending or borrowing action. That makes it lighter to maintain as an app, but it also means it may not protect me from poor financial habits. It supports a decision; it does not replace a complete system for managing money.
I would also keep the app updated on a compatible device and review the screens carefully whenever the experience changes. Finance products can evolve, and a familiar workflow should never become an excuse to skim over terms. The app’s age rating of Everyone makes it broadly accessible, but adults still need to make the financial judgment. Accessibility describes who can use the app, not who should borrow through it.
Where fatigue starts to appear
The main source of fatigue is the emotional weight of borrowing. Even if the interface is easy to understand, repeated visits can remind me that my income and expenses are not lining up. That is not a design flaw unique to Lenme, but it matters when judging whether the app deserves a permanent place on my phone. A tool that is useful during a crisis can become uncomfortable if I begin opening it automatically whenever money feels tight.
Another limitation is the temptation to focus on speed. The phrase “quick cash” is attractive when a bill is urgent, but speed can encourage shallow comparison. I would want enough time to read the full repayment details and consider what happens if my expected income arrives late. If the app makes me feel rushed, I would close it and use a slower alternative that gives me more room to think.
There is also a trade-off between specialization and completeness. Lenme is more relevant than a general finance tracker when I specifically want to explore personal lending opportunities. However, it is not the app I would choose as my main tool for building a household budget, monitoring every subscription, or planning long-term savings. For those jobs, a banking app, budgeting application, or spreadsheet may be more useful because those tools keep everyday money management at the center.
Potential lenders face a different kind of fatigue: evaluation. Looking at lending opportunities requires patience and a willingness to accept that attractive returns or convenient arrangements may involve risk. I would avoid treating the platform like a casual shopping app. The right mindset is closer to reviewing a financial commitment, with clear limits on how much money I can afford to place at risk.
In-app purchases are another reason I would remain attentive. The free price makes trying Lenme easy, but the presence of paid items means I would inspect prompts before confirming anything. I would not assume that a payment is required simply because it appears during the process, nor would I make a purchase just to speed up a decision. A finance app should be judged by the clarity of its costs as much as by the convenience of its main function.
Who will keep using it, and who should skip it?
I think Lenme is best suited to a borrower who wants to explore a personal loan or cash advance while remaining willing to compare alternatives. It may also suit someone interested in investigating lending opportunities and who understands that convenience does not equal certainty. The app is particularly reasonable as a “check before deciding” tool rather than an automatic emergency response.
I would skip it if I am looking for a full budgeting system, a normal checking-account replacement, or a guaranteed solution to ongoing financial shortfalls. I would also avoid borrowing through any platform if I cannot explain how and when I will repay the money. In that situation, the problem is not finding a faster app; it is that another obligation may make the situation worse.
Compared with asking a bank, Lenme may feel more focused on connecting users with borrowing and lending possibilities. Compared with a budgeting app, it offers less value for routine spending control. Compared with searching the web, it provides a more dedicated place to begin, but I would still verify every important term and compare the result with direct providers. Its best position is between those alternatives: more specialized than a general finance tool, but not a substitute for careful financial research.
My long-term verdict
Lenme: Borrowing and Lending earns lasting space on my phone only if I treat it as an occasional decision aid, not as a permanent answer to cash-flow problems. I appreciate the focused concept, the option to approach both borrowing and lending, and the way its AI-powered angle can make the first exploration feel more guided. The free entry point and broad compatibility also make it easy to keep available for the moment when I genuinely need it.
My reservation is equally clear: the app can simplify access to a financial opportunity, but it cannot simplify the responsibility that follows. The lasting value comes from using it with a written repayment plan, comparing alternatives, and setting a personal limit before emotion takes over. Without those habits, convenience may become a reason to borrow more often rather than a way to make better decisions.
My recommendation is cautious but positive: Lenme is worth trying for people who need a focused place to investigate personal borrowing or lending options, as long as they read carefully and keep control of the final decision. It is not the right long-term companion for budgeting, savings management, or unresolved recurring debt. For me, it survives the novelty test as a specialized tool—useful when the situation calls for it, but healthiest when I do not need to open it every month.
That balance is what makes the app worthwhile. I would keep it available, but I would not build my entire financial routine around it. Used selectively, Lenme can turn a stressful search into a more organized comparison. Used impulsively, it can make borrowing feel easier than it really is. The difference depends less on the app’s promise than on the discipline I bring to the screen.


